Al-Baghl: Real Estate Enters 'Sorting' Phase... Liquidity Shifts Direction as Investors Seek Returns
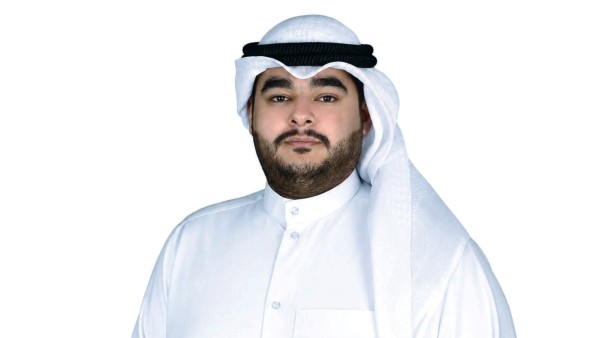
Expert Abdulhamid Al-Baghl confirms the end of the era of easy price hikes, with liquidity shifting towards commercial and residential properties in the outskirts.
Translated by Qiyas from السياسة — Original source
“Al-Siyasa” Monitors the Real Estate Landscape Amid Multiple and Rapid Changes
Private housing prices drop by 20%, influenced by vacant land fees
The era of easy price surges is over... Commercial sector leads the scene
Shortage of low-cost housing alternatives impacts the rental market
Real estate expert Abdulhamid Al-Baghlai confirmed that the Kuwaiti real estate market has entered a new phase, differing in nature from the boom years characterized by synchronized price hikes across most sectors. The market’s movement has become more selective, with liquidity now seeking returns and security rather than speculating on rising prices. Geopolitical tensions, rising construction costs, and tighter financing conditions have pressured real estate activity. Meanwhile, legislative changes, notably the implementation of the Vacant Land Law and expectations of an increased housing supply, have reshaped the demand and pricing landscape. The details follow:
In a special interview with “Al-Siyasa,” Al-Baghlai stated that the market has effectively entered a phase of “stability and calm” following the boom, emphasizing that “the era of easy price surges is over.” He noted that the Kuwaiti real estate market is now more selective, with opportunities varying between residential, investment, and commercial sectors according to each sector’s nature, location, and potential returns.
He explained that the general price index has faced recent pressure due to several overlapping factors, most notably regional tensions, rising construction and financing costs, alongside shifts related to housing policy and the implementation of the Vacant Land Law starting in January 2026. He clarified that the market no longer moves collectively as it did in the past, when price hikes affected most sectors simultaneously. Today, liquidity has become smarter and more cautious, flowing toward sectors perceived as better able to preserve value and generate returns. He summarized the current situation by stating that “liquidity has not disappeared from the market; it has merely changed its destination.” He pointed out that the investment sector is experiencing a relative outflow of liquidity due to caution, while the commercial sector attracts a larger share of funds seeking limited opportunities and lower supply.
Prices Between Real Value and Land Scarcity
Regarding price levels, Al-Baghlai observed that the current real estate market largely reflects “supply scarcity and government policies” rather than pure real estate value.
He explained that the implementation of the Vacant Land Law, along with expectations of launching approximately 140,000 housing units, has acted as influential factors in reassessing prices, particularly in the residential sector, where expectations of increased supply have led some buyers to wait.
News Services
Conversely, the investment sector has remained more resilient, even trending upward in some cases, due to the limited availability of good investment opportunities.
He noted that the shortage of low-cost housing alternatives has also impacted the rental market, particularly after the evacuation of areas such as Al-Husainiyah and Kuwait City 10. This has reduced the supply of low-priced units and driven up rents for some apartments.
Uneven Decline in “Residential” Prices
Regarding the difficulty of sustaining price declines in private housing in certain areas, he stated that prices have indeed fallen by approximately 20% in some areas beyond the Sixth Ring Road, influenced by vacant land fees and expectations related to subsidy removal and increased supply.
In the rental market, he said the market has already entered a repricing phase, though it differs across sectors. He clarified that the investment sector is seeing slight upward repricing, while private housing is trending toward stability or decline in some areas.
Real Estate Investment in 2026
Regarding the investment sector, Al-Baghl believes the current equation can be summarized by the phrase: "Fixed returns, but variable costs."
Land or Building? ... Wealth lies in the former, income in the latter.
When weighing the choice between buying land or a building, Al-Baghl asserts that "land creates wealth, while buildings generate cash flow." He explains that land remains a tool for long-term wealth building, particularly given land scarcity and the lack of new plots released in some areas. He noted that commercial land prices rose by 3.6%, despite pressures affecting other sectors.
Furthermore, in his view, land is distinguished by lower operating costs compared to built properties, as there are no maintenance, electricity, or tenant management expenses associated with it.
On the other hand, an investment building provides investors with monthly income, potentially yielding rental returns ranging between 6% and 6.5%. He stated that those seeking to build long-term wealth should consider land, particularly commercial and investment plots in prime locations, while those seeking monthly income may find their solution in built investment properties.
Conversely, he warned against combining rising land prices with high construction costs and heavy reliance on financing. He considered buying expensive residential land and then financing its construction with a loan to be one of the most costly scenarios under current conditions, due to the simultaneous rise in financing and construction costs.
2.16 Billion Dinars in the First Half... But the Liquidity Landscape Has Changed
Regarding liquidity sources and trends, he confirmed that funds are present in the market, but they have become more cautious due to regional tensions and higher financing costs. He pointed out that the total market value reached approximately 2.16 billion dinars in the first half of 2026, although liquidity channels have shifted significantly.
He stated that current liquidity stems from three main sources:
1. Citizen liquidity, which is flowing into the residential sector, particularly in lower-priced areas, driven by housing needs and anticipation of housing support. This explains the rise in the number of residential transactions despite a decline in sales value.
2. Liquidity from major companies and funds, which is increasingly directed toward the commercial sector in search of limited opportunities and scarce supply.
3. Liquidity from wealthy families and traditional investors, who continue to hold a portion of the investment sector, particularly existing properties with stable rental yields.
He noted that, conversely, the market is witnessing a clear decline in the presence of speculators and buyers who rely on financing, due to rising interest rates.
Thus, the main destinations for liquidity have become three: the commercial sector, which serves as a relative haven amid limited supply; existing investment properties, which offer stable returns; and residential properties on the outskirts, where citizens seek lower prices.
Interest Rates... The Market's Primary Brake
Al-Baghlali confirmed that financing costs have become one of the most influential factors affecting the Kuwaiti real estate market in 2026, stating that “interest rates today are the market’s primary brake.” He explained that stricter financing conditions and rising costs have slowed demand momentum and reshaped investors’ decisions, particularly those relying on borrowing to achieve returns. He added that the market was previously more receptive to buying with financing and waiting for asset value appreciation, whereas today, investors are more focused on the spread between financing costs and the returns generated by the property. Nevertheless, he believes the coming months may bring greater stability if interest rates are cut, alongside the implementation of the anticipated mortgage financing law, which could enhance financing capacity and restore some demand to the market.
Summarizing the landscape, according to Al-Baghlali’s assessment, the Kuwaiti real estate sector is not experiencing a liquidity disappearance but rather a “re-sorting”; funds remain available but have become more selective. Buyers are no longer chasing price increases but are instead seeking location, returns, and future liquidity, while financing costs have become a decisive factor in determining whether a deal is a genuine opportunity or a long-term burden.
Current demand map... Three main patterns
The real estate expert believes that one of the most significant changes in the market is the shift in buyer identity, noting that “the buyer today is not necessarily the same as the one who bought three years ago.” He currently identifies three main buyer patterns:
● First: The citizen seeking housing, who is more closely tied to the private residential sector. Demand is concentrated in areas with relatively lower prices, particularly Ahmadi and Jahra, amid long waiting periods for housing allocation. With the implementation of the Vacant Lands Law, this buyer has become more price-sensitive, seeking the “cheapest suitable price” rather than the best investment opportunity.
● Second: The conservative investor, concentrated in the investment sector, including companies and families with liquidity seeking to hedge against inflation. Demand is focused more on areas such as Hawalli, Salmiya, and Farwaniya, particularly in older buildings with stable rental cash flows, where yields of 6% and 6.4% make some opportunities attractive in current conditions, as investors now prefer “clear returns” over speculation and risk.
● Third: The institutional investor, comprising large companies, funds, investment portfolios, and major traders, who are increasingly targeting the commercial sector, particularly in Kuwait City, Salmiya, and Fahaheel, focusing on shops and offices, benefiting from the scarcity of good commercial land.
On the other hand, investors face rising construction and financing costs, as well as declining sales due to buyer caution. However, the sector remains “relatively attractive” to investors seeking steady income and inflation hedging, particularly if purchases are based on return analysis rather than solely on expectations of price appreciation.
