Kuwait Participates in Asian Investment Bank Meetings Chaired by Finance Minister - Sarmad
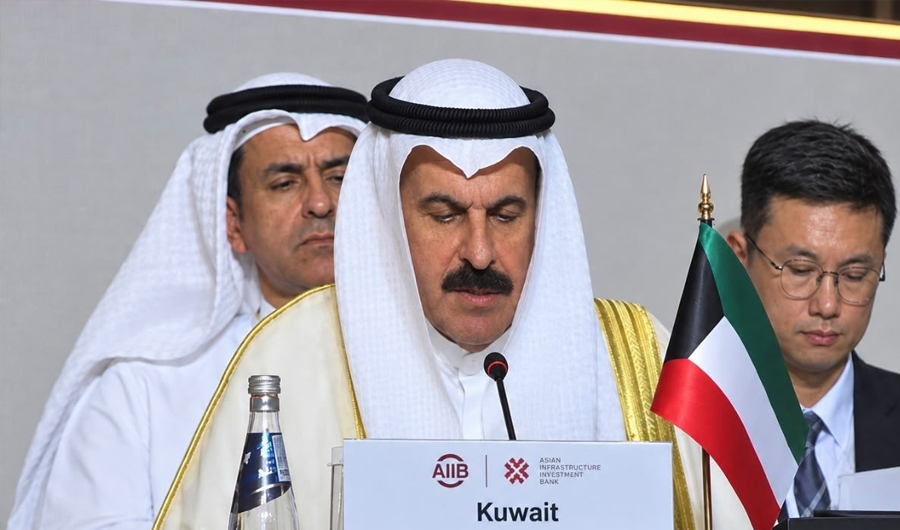
(KUNA) — Kuwait participated today, Monday, in the 11th Annual Meeting of the Board of Governors of the Asian Infrastructure Investment Bank (AIIB), led by a delegation headed by Minister of Finance Dr. Yaqoub Al-Rafai.
The two-day meeting was held under the patronage and in the presence of Qatari Prime Minister and Minister of Foreign Affairs Sheikh Mohammed bin Abdulrahman Al Thani, and AIIB President Zou Jiayi. It was attended by Kuwait’s Ambassador to Qatar, Ahmed Al-Sharrah, alongside finance ministers, governors, delegations from member countries, senior experts, private sector leaders, and civil society organizations.
The meeting is held under the theme “Infrastructure for Tomorrow: Impact and Innovation.” This year’s sessions hold particular significance as they mark a key milestone in the transition of the AIIB into its second decade, amid rapid economic and financial changes that necessitate strengthening the role of development finance institutions, developing their tools and operational mechanisms, and enabling them to respond to the needs of member countries, support sustainable and innovative infrastructure projects, and achieve greater developmental impact.
These meetings coincide with the 10th anniversary of the Bank’s operations, representing a checkpoint to evaluate achievements, review priorities for the next phase, and chart the strategic direction for the Bank’s second decade. The meeting highlights the pivotal role of the Middle East region in enhancing inter-regional connectivity and cooperation.
Minister Al-Rafai participated in a session dedicated to the Board of Governors, during which decisions related to the Bank’s operations were adopted and its strategic initiatives for the coming years were reviewed. He also took part in a roundtable discussion alongside ministers and governors of the AIIB.
In his speech, Minister Al-Rafai affirmed Kuwait’s belief in the importance of the role of development banks in addressing economic changes that have cast shadows over many countries and affected development progress and economic growth rates. He emphasized the need to enhance coordination and cooperation among international financial institutions to bridge financing gaps, unify efforts to support member countries, and enable them to implement their development projects. He also stressed the importance of providing technical support and necessary expertise to prepare bankable and executable projects that contribute to achieving sustainable developmental impact.
The Kuwaiti delegation, led by the Minister of Finance, included Saad Al-Rashidi, Director General of Economic Affairs and Alternate Executive Director on the Board of Directors of the AIIB; Ibrahim Al-Filikaawi, Director of the International Economic Cooperation Department; and several officials from the Kuwait Fund for Arab Economic Development.
Kuwait’s participation in the meeting comes within the framework of its commitment to enhancing its role and contribution to the Bank’s work and strengthening partnerships with international and regional financial institutions.
Earlier, Qatari Minister of Finance and Chairman of the AIIB Board of Governors for 2026, Ali Al-Kuwari, stated in his speech marking the launch of the meeting that Qatar was among the founding members of the Bank in 2015, driven by its conviction that Asia needed a new institution focused on infrastructure development, governed by the highest standards, and open to the entire world. Al-Kuwari added that after 11 years, with the Bank’s membership reaching 111 members and approved financing totaling approximately $70 billion, this belief has been proven correct.
For her part, AIIB President Zou Jiayi affirmed that the Bank aims to expand its developmental impact and nearly double its annual financing volume by 2030, reaching approximately $20 billion, with a focus on financing future infrastructure. She added that the Bank’s objective in the coming phase is to expand its developmental impact through innovation and integrity, noting that achieving this goal requires increasing the Bank’s business volume and leveraging areas where it holds a comparative advantage.
