Al Ahli: Implementing Plans According to Strategic Priorities
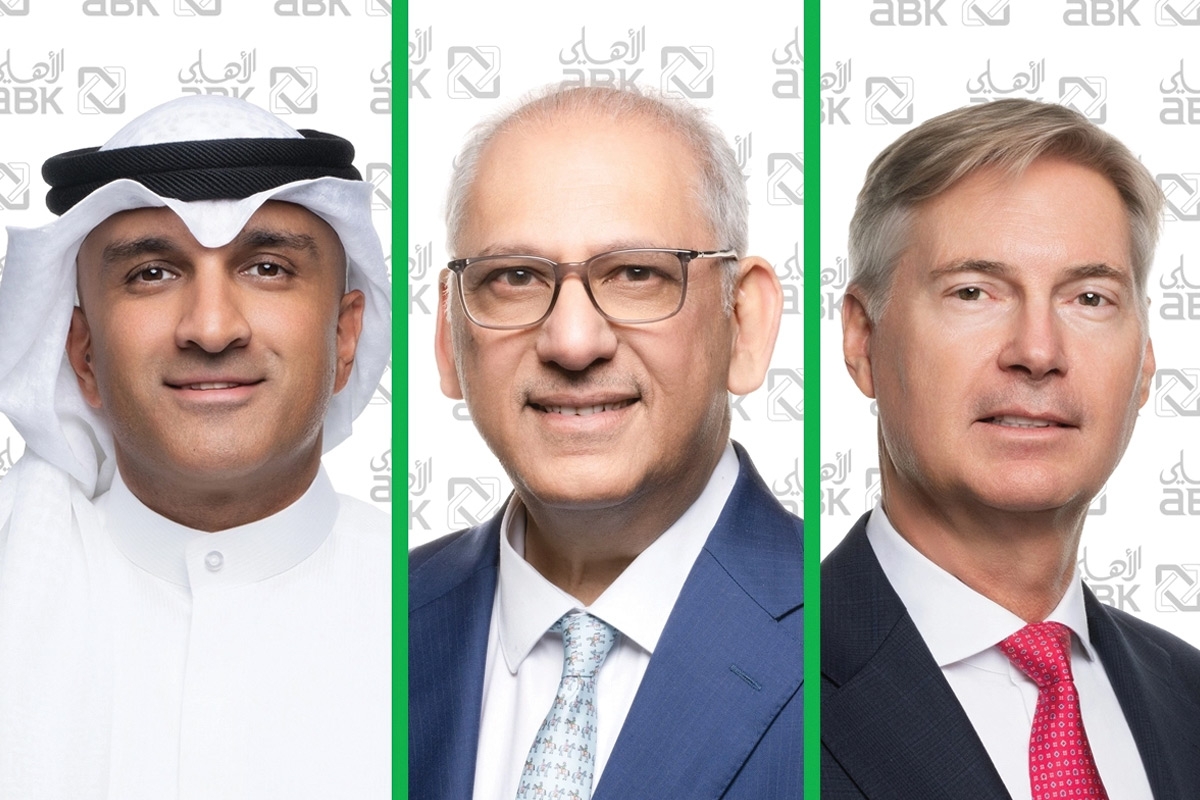
Kuwait National Bank Al Ahli Group achieved profit growth and improved credit indicators, with capital increase approval from the Central Bank and Capital Markets Authority, and maintained Moody's and Fitch ratings.
Translated by Qiyas from الجريدة — Original source
Kuwait National Bank (KNB) Group held its analysts’ conference to discuss the results for the first nine months of the current year, with participation from Group Chief Executive Officer Geert van der Toel, Chief Financial Officer Shyamak Sunawala, Head of Strategic Planning and Follow-up Dr. Abdulaziz Jawad, and Assistant General Manager of Strategic Planning and Follow-up Osama Ezzeldin, to explain the recorded financial indicators and the Group’s future strategic plans.
On this occasion, Van der Toel stated that KNB maintained its positive momentum during the first nine months of 2026, continuing to expand its lending operations, boost profits, and improve asset quality, supported by a disciplined approach to risk and balance sheet management. He added that the Group’s priorities at the start of the fourth quarter of the year include selective business growth, maintaining asset quality, disciplined capital allocation, and executing plans in line with strategic priorities.
He continued: “During the first nine months of the year, we focused on meeting customers’ financing needs, strengthening relationships with them, and selectively expanding the Bank’s business in our markets.” He noted that net profit attributable to shareholders rose by 16.2% year-on-year to KD 54.2 million, while earnings per share increased to 17.6 fils.
He indicated that credit quality indicators remain strong, with the non-performing loans ratio declining to 1.19% from 1.29% in September 2025, while the provision coverage ratio reached 355%. Additionally, the cost of risk improved to 0.82%, compared to 1.06% a year ago. He added that capital and liquidity are in a solid position, with the Group’s capital adequacy ratio recorded at 17.25% in September 2026, the Tier 1 capital adequacy ratio at approximately 13.65%, and the Common Equity Tier 1 (CET1) ratio at 11.94%, while the liquidity coverage ratio stood at 184%.
Van der Toel pointed out that the Bank is working to expand its capital base to support future growth and implement its new five-year strategy. Shareholders approved in September an increase in KNB’s authorized capital from KD 274.9 million to KD 600 million, providing greater flexibility to meet future capital requirements and business opportunities.
He added: “We obtained the required approvals from the Central Bank of Kuwait and the Capital Markets Authority for an increase in issued and paid-up capital by KD 75 million, or 27.29%, bringing it to KD 349.9 million, through the issuance of 750 million shares at a price of 200 fils per share, including an issue premium of 100 fils. The increase amounts to KD 150 million, divided into KD 75 million nominal value and KD 75 million issue premium. This increase is expected to improve the CET1 ratio and capital adequacy ratios by approximately 280 basis points, while providing additional capacity to support growth while maintaining appropriate capital buffers.”
He emphasized: “We continue to invest in digital infrastructure and develop artificial intelligence capabilities to enhance customer experience, improve operational efficiency, and support product development in line with evolving customer needs across all markets in which we operate.” He added: “Our credit ratings have remained stable, with Moody’s confirming KNB’s rating at A2 with a stable outlook, while Fitch confirmed the Bank’s rating at A with a stable outlook. These strong ratings support the Bank’s creditworthiness.”
He added: “Our employees remain a pivotal element in the performance of Kuwait Finance House and the execution of its strategy, and we continue to develop leadership capabilities and foster a culture of responsibility and high performance standards across the Group. Kuwaitis hold approximately 67% of leadership positions, while women constitute 41% of the workforce. Developing local talent and maintaining an inclusive work environment remain among our priorities, as we provide the necessary capabilities to support the Group’s growth plans. Based on what has been achieved, 2027 will be a year of expansion in our business and delivering the best sustainable returns to our shareholders.”
For his part, Sonawala stated: “We maintained positive momentum during the first nine months of 2026, driven by profit growth and stable operational performance. Our performance demonstrates sustainable progress across the Group’s departments overall, amidst rising profits and balance sheet growth, improved asset quality, while capital and liquidity remained at comfortable levels. We will continue to sustain this momentum and deliver sustainable returns to our shareholders.”
He noted that net profit attributable to shareholders grew by 16.2% year-on-year to KD 54.2 million, while earnings per share increased by 18.1% to 17.6 fils. “Return on average shareholders’ equity also improved by 87 basis points to reach 9.33%, supported by higher profits and the performance of our core banking activities.”
He highlighted that operating income rose by 7.5% year-on-year to KD 177.5 million, primarily driven by an 11.3% growth in net interest income. Meanwhile, lower funding costs widened the net interest margin by 24 basis points to 2.50%, which led to a 5.5% increase in operating profit to KD 100.3 million, maintaining positive operational momentum.
He continued: “The cost-to-income ratio stood at 43.5%, an improvement of 30 basis points compared to 43.8% recorded at the end of 2025.” He explained that corporate banking remained the largest contributor to operating income at 44%, followed by retail banking at 34%, and treasury and investment at 22%, providing a diversified profit base across the Bank’s core activities.
Sonawala pointed to the maintenance of a strong capital position, with a capital adequacy ratio of 17.25% and a Common Equity Tier 1 (CET1) ratio of 11.94%, both significantly above regulatory requirements, providing ample margin to support the Bank’s business and strategic priorities. He revealed further improvement in credit quality metrics during the quarter, with the non-performing loan ratio declining to 1.19%, reflecting a conservative approach in managing the financing portfolio.
He added: “Provision coverage increased to 355%, compared to 340% in the previous quarter. We maintained loan provisions in accordance with Central Bank of Kuwait directives and exceeded the requirements of International Financial Reporting Standard 9 (IFRS 9) by KD 200 million, providing a strong buffer against potential credit pressures.”
He concluded: “Our balance sheet has maintained a balanced growth pace since December 2025, with total assets growing by 8.6% to KD 7.5 billion. Loans and advances increased by 10.2% to KD 5 billion, while customer deposits rose by 5.5% to KD 4.3 billion. The liquidity coverage ratio stood at 184% and the net stable funding ratio at 118%, both significantly above regulatory requirements, providing us with ample liquidity margin.”
For his part, Dr. Abdulaziz Jawad stated: “Our core operational activities in Kuwait reflect high performance and resilience despite the challenges posed by the operating environment. In corporate banking, the low-cost deposit portfolio recorded notable growth, and we maintained our disciplined focus on asset quality, sustainable returns, pricing policies, and capital efficiency, despite the pressures exerted by regional conditions on trade flows.”
He added: “We expanded our core customer base of salaried employees and continued to grow the number of high-net-worth clients, adhering to prudent credit controls. We launched three new cards for corporates and small and medium-sized enterprises (SMEs), offering cashback benefits and the Visa Spend Clarity service, as well as virtual cards designed to complement our Merchant and Merchant Plus offerings, thereby enriching our business-oriented solutions.”
He noted that Kuwait Finance House (KFH) continues to develop its home financing program, “ABK Build,” aiming to meet customers’ financing needs and enhance their end-to-end experience by providing all relevant services they may require.
He added that this comes as a proactive step by the bank to confirm its full readiness to capitalize on the new mortgage law, the draft of which was recently issued. The law approves two financing models for eligible beneficiaries seeking housing support: subsidized and non-subsidized financing, with the option to combine them according to regulations set by the Central Bank of Kuwait. The key next step is the issuance of the executive regulations within six months of the law’s publication to define the detailed operational framework, including the cap on subsidized financing and the governing procedures. The law will enter into force immediately upon the publication of these regulations.
He clarified that ABK Wealth Management, the investment arm of the group, continued to develop its solutions for clients by launching a new digital application that enables seamless digital onboarding to its client base, while providing investment dashboards and advanced analytics, as well as easy access to a broad portfolio of investment solutions. He also highlighted its continued expansion in investment services through active engagement in regional financial markets.
Jawad stated: “The Capital Markets Authority approved the prospectus for the issuance and payment of KFH’s capital increase on October 21. The timeline has been finalized, with the subscription period running from November 8 to 22. The full timeline, including due dates and trading dates for subscription rights, can be viewed in our disclosures published via the Kuwait Stock Exchange, the KFH website, and the ABK Wealth Management website. We confidently look forward to the continued support of our shareholders, as the additional capital will drive the next phase of our growth.”
He concluded: “The group is nearing the completion of its updated five-year plan, with the strategy enriched across all our markets and core businesses, maintaining a steadfast focus on sustainable growth, disciplined capital distribution, and improved returns.”
He stated: “Our future focus remains on the disciplined execution of our strategy across the various markets in which we operate, strengthening our customer relationships, enhancing operational efficiency, and building capabilities that support growth. We will continue to adopt a selective approach to resource allocation and risk management tailored to each market.” He added, “The progress we have achieved so far provides us with a solid foundation and the confidence to continue implementing our priorities through the remainder of 2026 and into 2027.”
