Kuwait... From Asset Ownership to Maximizing Their Value
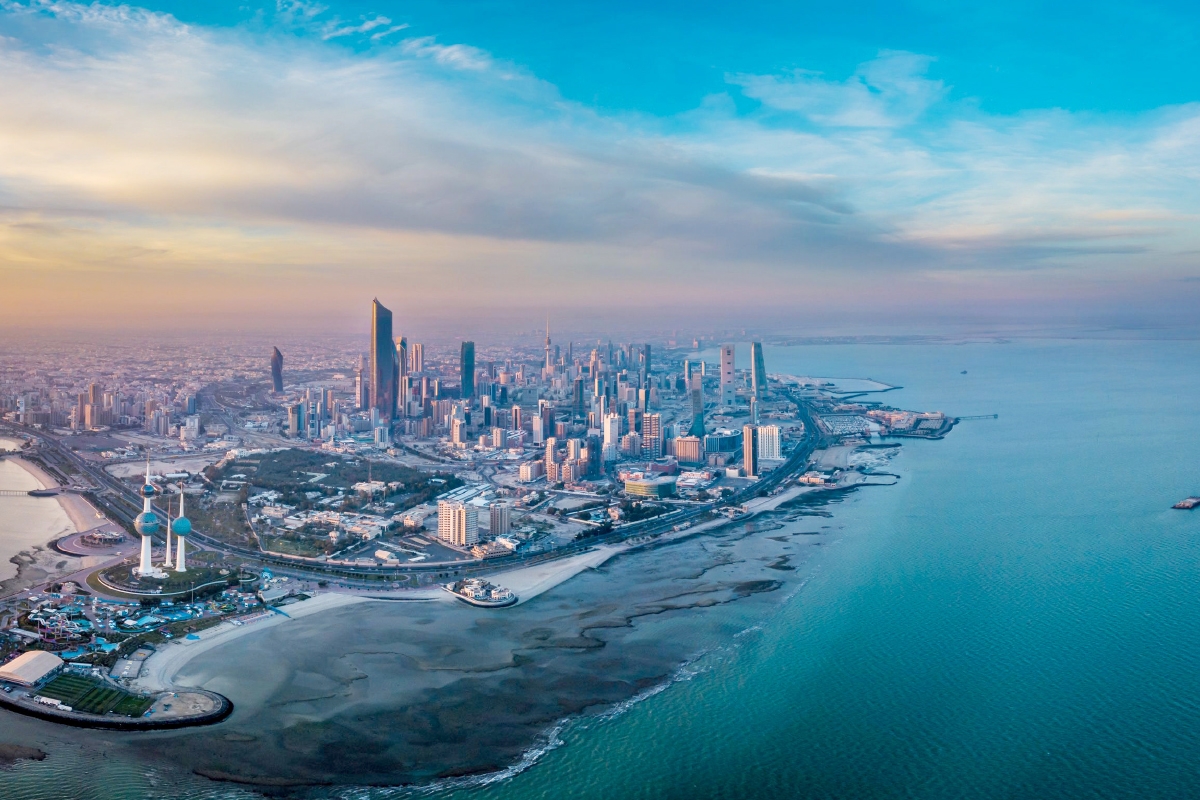
An analysis urges Kuwait to shift from asset ownership to maximizing economic value by boosting productivity and selecting partners based on efficiency and measurable results in the oil, water, energy, and industrial sectors.
Translated by Qiyas from الجريدة — Original source
After decades of investment, Kuwait possesses substantial oil reserves, modern refineries, a petrochemical base, energy and water infrastructure, significant sovereign capital, and financial institutions capable of funding. However, the question that must precede any new project is: Do these assets yield the highest possible economic return for Kuwait?
This represents the required shift in decision-making: from measuring what we spend, build, and produce, to measuring the productivity, cash flows, and return on capital generated by our assets.
Success is not reaching four million barrels per day if the additional barrel is high-cost; nor is building a larger water plant if a cubic meter can be produced at a lower cost; nor is adding a power plant if fuel can be saved to achieve higher value; nor is building a factory simply because raw materials are available if exporting them yields a better return.
Every asset must answer one economic question: Can this dinar, barrel, cubic meter, or unit of energy achieve higher value in an alternative use?
Consequently, priority should not lie in creating new institutions or increasing expenditure, but in enhancing the productivity of existing assets, reallocating capital toward higher-yield uses, and halting activities that lack economic viability.
This requires a state that sets priorities, selects the best partner for each task, links technology with knowledge transfer, grants management authority in exchange for measurable results, and places efficiency before courtesy, viability before projects, and returns before investment size.
This vision rests on six interconnected pillars: oil, water, energy, industry, finance, and leadership. Each pillar has different criteria, but the equation remains the same:
In oil, we seek proven expertise in similar reservoirs; in water, technology that reduces the cost per cubic meter and energy use; in industry, technology, knowledge, product adoption, and market access; and in finance, expertise in risk, capital structuring, and governance.
The criterion is simple: we do not choose a foreign partner because they are foreign, nor a global company because of its large name. We choose them because they have done what we want to do before, with measurable results.
The goal is for Kuwait to become more capable of operations, development, and decision-making after partnerships than it was before.
Kuwait Petroleum Corporation’s strategy targets a sustainable oil production capacity of 4 million barrels per day by 2035, maintained until 2040, along with producing 2 billion cubic feet per day of non-associated gas by 2040, alongside 14.5 million tons annually of petrochemicals and 1.2 million tons of derivatives.
In heavy oil, Chevron offers significant practical expertise. At Burgan, steam injection was tested experimentally in the carbonate Eocene reservoir in 2009 to assess the technical and economic feasibility of thermal recovery, while the full-scale implementation phase was designed with a capacity of approximately 100,000 barrels per day.
In more complex reservoirs, Kuwait Oil Company awarded SLB a $1.5 billion, five-year contract in February 2026 for design, development, and production management in the Murayban field, which features deep, high-pressure, high-temperature, and sour conditions.
Therefore, Chevron, ExxonMobil, Shell, and bp can be selected based on the specific problem, and specialized service and technology companies can be leveraged where they add clear value.
As oil production rises, the importance of associated water increases. Therefore, the reservoir, well, oil, gas, and water must be treated as a single production system, with water treatment measured by cost, energy consumption, separation efficiency, reinjection performance, and its impact on the reservoir.
Treated water can also be reused in industry, cooling, afforestation, and other suitable applications, thereby reducing demand for more expensive desalinated water.
A study based on actual operational data at Al-Shaqiya indicates a levelized cost of electricity of approximately 15 fils per kilowatt-hour for wind and 27 fils for photovoltaic solar energy. These figures reflect the project and technology costs at that time, not the expected prices for new projects following the significant global decline in renewable energy costs.
Therefore, the question is not how many power plants we should build, but rather what mix will provide Kuwait with reliable electricity at the lowest economic cost. The most viable approach is combining solar and wind in suitable locations, along with storage and high-efficiency gas power plants to ensure grid flexibility.
Crucially, every barrel of oil or unit of gas not burned to generate electricity can be exported or directed toward higher-value industrial uses. Thus, renewable energy should not be measured solely by its cost per kilowatt-hour, but also by the value of the fuel it saves.
Kuwait is advancing along this path through the Al-Dabdaba-Al-Shaqiya solar energy project, with a capacity of 1,100 megawatts, which reached an advanced stage of development and bidding procedures in 2026.
Fourth: Post-EQUATE... From Basic Materials to Higher-Value Industry
Kuwait has built a global petrochemical base through EQUATE, part of a group with production assets in Kuwait and abroad whose announced capacity exceeds six million tons annually. The question now is not merely to produce more basic materials, but to leverage this base to build higher-growth, higher-value industries.
However, not everything that can be manufactured warrants investment. Priority should be given to industries that combine raw material availability, global demand growth, technical barriers, export capability, and economic margin and viability.
The natural starting point is Dow, the existing strategic partner of EQUATE. This partnership can be expanded from basic petrochemicals to downstream industries where Dow’s expertise in materials science and advanced applications intersects with materials produced in Kuwait.
Depending on the product, other global partners can be considered. The criterion is not the partner’s name, but what it adds in terms of technology, higher-value products, global specifications, clients, or export markets. When a partner’s contribution is strategic, it is preferable for it to also invest equity.
Does converting materials in Kuwait yield a higher Return on Invested Capital (ROIC) than exporting them, after accounting for risks and the cost of capital?
This begins with clarifying the off-take: volumes, specifications, pricing, contract duration, and supply continuity. It also requires an integrated industrial infrastructure providing land, energy, water, services, storage, and port connectivity, while clustering interrelated industries to reduce costs and logistics burdens.
State ownership of capital does not mean the government must finance every project.
In suitable projects, Project Finance can be used, where cash flows, sales contracts, off-take agreements, technology, and the project’s debt-servicing capacity form the basis of financing, rather than government guarantees.
Global institutional investors can also bring discipline in investment evaluation, risk structuring, governance, and access to capital markets. However, capital alone is not a reason for partnership if Kuwait can provide it at a lower cost.
No financing without feasibility, no factory without a market, no guarantee to mask a weak project, and no permanent support for an industry unable to compete.
Here, the language of measurement becomes unified: the cost of the additional barrel of oil, the cost per cubic meter of water, ROIC in industry, and cash flow and risk-adjusted returns in financing.
This applies to boards of directors. Before selecting names, a Board Skills Matrix is established to identify the expertise required in the sector, projects, finance, capital allocation, technology, markets, risks, and governance, after which the best person is chosen for each board seat.
However, competence is insufficient without authority. There must be a clear separation between the state as owner, the board of directors as the guiding and supervisory body, and the executive management as the decision-making and implementing entity.
The CEO must be able to select their team, replace a weak partner, reallocate capital, and halt a project whose viability no longer justifies its continuation. A good decision may sometimes be not to invest, to exit, or to redirect capital.
Conversely, there is no authority without accountability. Before allocating any dinar, the cost of capital, risks, cash flows, timeline, and stop-loss conditions must be defined. After implementation, management is measured by Return on Invested Capital (ROIC), cash flow, productivity, cost, execution speed, and Economic Value Added (EVA).
Governance must simply answer: Who decides? Who executes? Who monitors? And who bears the outcome?
Management cannot be held accountable for a decision they lacked the authority to make, nor can authority be granted without independent measurement and accountability.
Kuwait does not start from scratch. It possesses resources, assets, capital, and institutions. Therefore, it is no longer convincing to measure success by the volume of spending or the number of projects announced and built. The standard that should govern the next phase is: What economic value do these assets generate for Kuwait?
In oil: the value of the reservoir, not the number of wells.
In energy: the cost of electricity and the value of saved fuel, not the number of power plants.
In industry: competitiveness and exports, not the number of factories.
The difference between owning wealth and building a productive economy lies in the quality of decision-making. A resource not directed to its highest-value use represents a missed opportunity, and capital remaining in a weak project carries a cost. Delay in decision-making has a price, and continuing a project that has lost its viability is not preserving investment but depleting it.
Therefore, the question before and after every project must become one: What return did we achieve compared to what could have been achieved from the same asset and capital?
If a global partner adds technology, markets, or productivity, we engage them and transfer knowledge. If a project yields a return exceeding the cost of capital and available alternatives, we invest and expand. If it does not, it should not be protected by the budget, the institution’s name, or funds spent on it in the past.
A sound economic decision is not always about building a new project. It may involve increasing the productivity of an existing asset, reallocating capital, changing a partner, halting a project, or simply not investing.
Kuwait has sufficient assets for the current question to be more rigorous: What have these assets actually achieved, and what could they have achieved but did not?
This is the accountability required for the next phase.
An economic and industrial renaissance is not measured by the billions spent, but by the value remaining after spending; not by the barrels produced, but by the return extracted from them; not by the number of factories built, but by their ability to compete and export; and not by the authorities granted, but by the results achieved.
Ultimately, Kuwait suffers less from a lack of resources than from a test in how to convert what it possesses into higher value.
From wealth management to holding every dinar accountable for the value it created.
