When a company contracts with a 'market maker'... what does the announcement actually say?
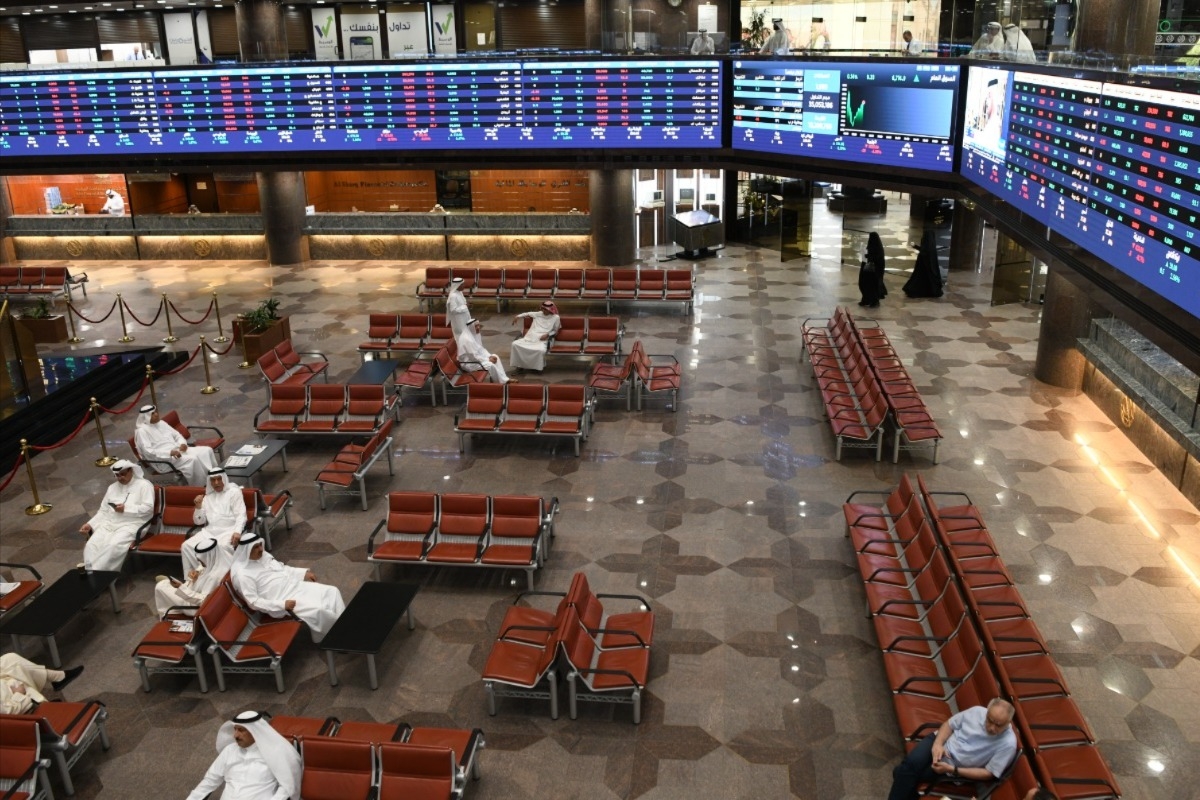
An academic study shows that Kuwait Stock Exchange companies contract with market makers to improve liquidity and transition to the first market or maintain their classification
Translated by Qiyas from الجريدة — Original source
When a company listed on the Kuwait Stock Exchange announces its engagement with a market maker, the announcement may initially appear to be a technical move aimed at boosting trading activity in the stock. However, data suggest that the timing of the decision and the company’s position relative to classification requirements may reveal more specific motivations.
For main market companies, the tendency to engage a market maker increases as the company approaches meeting the requirements for transition to the first market, particularly if it has already satisfied the market capitalization requirement but still needs to improve its liquidity level.
In the case of first market companies, engagement with a market maker becomes more prominent when the company faces pressures related to maintaining its listing status, especially if it has been placed on or is approaching the list of companies under continuous compliance monitoring.
An academic study examining the market maker industry at the Kuwait Stock Exchange reveals that the decision to hire a market maker is not solely driven by a general desire to increase stock activity, but may also be part of a strategic move linked to the company’s position regarding upgrade requirements or its continued presence in the first market.
Proximity to the “First Market” Stimulates Engagement: Results showed that main market companies close to meeting the liquidity requirement for transition to the first market were more likely to engage a market maker compared to companies that had already met the requirement or those that remained far from it.
During the period covered by the study, transitions between the two markets were associated with criteria including market capitalization and average daily trading value, while engagement with a market maker remained optional.
This implies that the importance of a market maker may rise specifically when a company has already covered a significant portion of the path toward an upgrade, and improving stock trading activity becomes one of the remaining requirements.
This association was most evident among companies that had met the market capitalization requirement, indicating that interpreting an engagement announcement requires understanding which requirements the company has already fulfilled and which it still needs to meet.
According to the study’s results, the presence of a market maker was associated with an approximately 12 percentage point increase in the likelihood of the company meeting the liquidity requirement, after controlling for various company characteristics and other factors included in the analysis.
Furthermore, the relationship observed in the study is a statistical correlation and does not necessarily imply that engaging a market maker alone is the direct cause of the company’s improved status.
The study, published in the international scientific journal Research in International Business and Finance under the title “Sharia Compliance and Strategic Determinants of Market Maker Engagement: Evidence from a Segmented Emerging Market,” found that being listed on the continuous compliance monitoring list was associated with a higher likelihood of having a market maker agreement in the year of listing on the monitoring list or the preceding year.
The estimated increase in the likelihood of having such an agreement ranged from approximately 19 to 32 percentage points, depending on the model used in the study.
The continuous compliance monitoring list includes companies subject to monitoring due to non-compliance with one of the requirements for maintaining their first market listing, exposing them to the risk of downgrading if the non-compliance persists. This makes the increased likelihood of engagement in such cases consistent with the company’s attempt to support its stock’s liquidity and maintain its listing status.
However, this result does not imply that hiring a market maker guarantees the company’s continued presence in the first market. The study measured the decision to engage, but did not measure the market maker’s success in preventing a downgrade.
Thus, an announcement by a company about contracting with a market maker may warrant scrutiny beyond the service provider’s name and the agreement’s duration.
If the company is in the primary market, it becomes important to assess how close it is to meeting the requirements for upgrading to the first market, and whether liquidity levels constitute the remaining obstacle to its transition.
If the company is in the first market, it may be useful to verify whether it is facing pressures related to listing maintenance requirements or has previously been placed on a watchlist for ongoing compliance.
This does not imply that all agreements were entered into for these reasons; rather, the findings suggest that the company’s position relative to classification requirements was a factor associated with the decision to contract during the study period.
Other factors influencing the decision may include contract costs, negotiations with the market maker, changes in the company’s needs, or the achievement of the objective for which the agreement was made.
Notably, the study also found that the stock’s classification within liquidity buckets was not, in itself, a clear factor in explaining the company’s decision to contract with a market maker after accounting for other characteristics. This suggests that the decision does not rely solely on the stock’s liquidity level but is influenced by a broader set of factors, including the company’s position relative to classification requirements and its objectives related to improving stock trading.
A market maker refers to a licensed entity that continuously provides buy and sell quotes for a stock under specific regulations, thereby facilitating trading, enhancing stock liquidity, and narrowing the bid-ask spread. Here, liquidity refers to the ease of trading the stock in the market, not the amount of cash available to the company.
Companies operating in accordance with Shariah principles and having institutional Shariah compliance arrangements were less likely to contract with market makers compared to other companies, after controlling for company characteristics, liquidity, and trading activity.
Conversely, no significant differences were observed among Shariah-compliant classified companies in their decision to engage a market maker compared to non-compliant companies. The study suggests that variations across company categories may be linked to differences in investor bases, governance arrangements, or other contractual considerations, without any single factor being definitively identified as the primary cause.
The findings were based on an analysis of 110 market-making agreements entered into by 62 listed companies with nine market makers during the period from 2019 to 2024.
By the end of the study period, 47 companies maintained at least one active agreement, representing approximately one-third of the listed companies at that time.
The study was conducted by Dr. Saad Al-Nahid, Dr. Khaled Al-Sabah, and Dr. Saud Al-Thaqabi, faculty members in the Finance Department at the College of Administrative Sciences, Kuwait University.
