Al-Shal Report: Saudi Market Leads Losers in September... Dubai Biggest Gainer
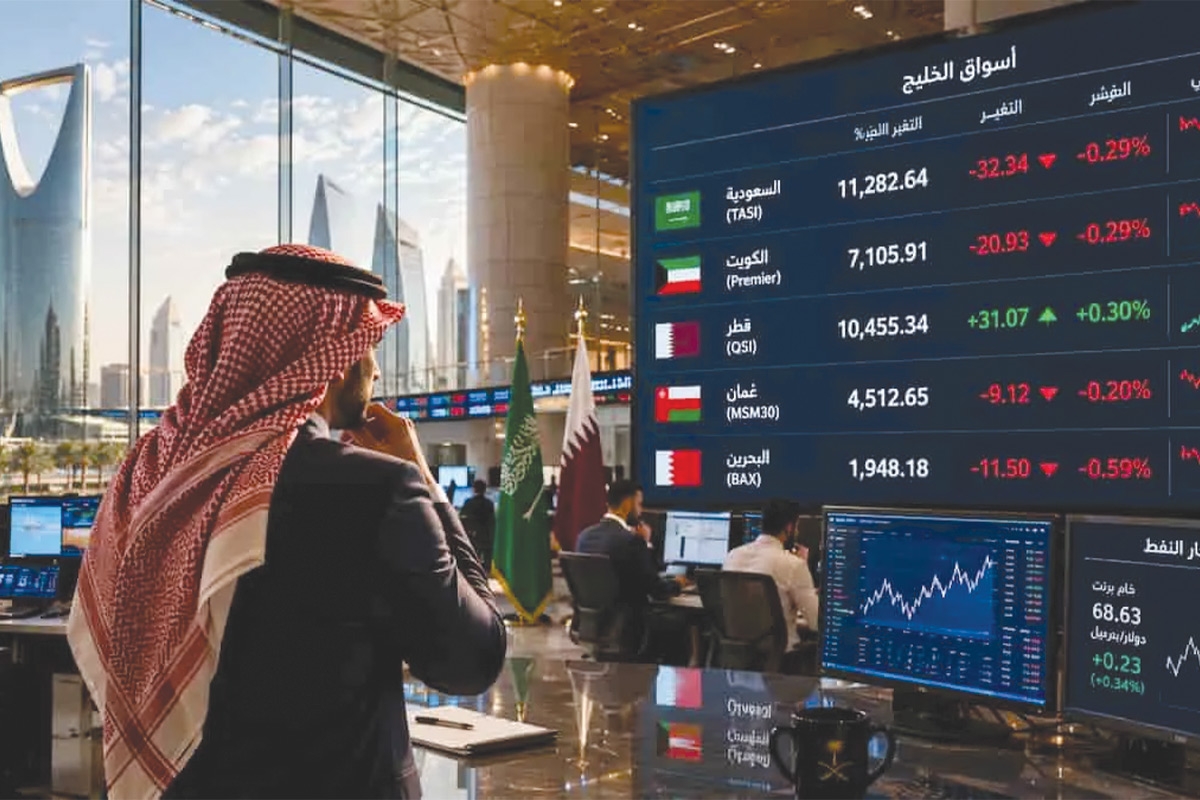
The Al-Shal report revealed negative performance for sample markets in September, with the Saudi market leading the losers with a 6.2% loss, while the Dubai market recorded the highest gains. The report expects October to be affected by the US elections and relations with Iran.
Translated by Qiyas from الجريدة — Original source
The performance of the sample markets in September was negative, with indices in 11 markets declining while those in 3 markets rose, compared to their levels at the end of August. Compared to their levels at the end of 2025, negative performance also predominated, with markets split between 8 losers and 6 gainers.
According to the "Al-Shal" report, the top gainer in September was the Dubai market, whose index gained approximately 2.1%, reducing its year-to-date losses to around -1.4%. It was followed by the Japanese market, which posted gains of 0.9%, remaining the top gainer year-to-date with a return of 32.9%. The Abu Dhabi market achieved gains of approximately 0.6%, making it the weakest gainer year-to-date with a return of 0.8%.
On the other hand, the Saudi market led the list of losers, with its index falling by approximately 6.2%, moving into negative territory with year-to-date losses of around 0.5%. It was followed by the Indian market, which recorded losses of 5.8%, ending the first nine months of the year with the highest losses among the sample markets at -14.9%. The Qatar Stock Exchange recorded losses of 5.7%, followed by the French market at -4.4% and the US market at -4.3%. The German market posted losses of 4.0%, the Chinese market 3.6%, and the UK market 2.0%. The Bahrain Bourse index declined by 1.5%, the Kuwait Bourse by 1.3%, and the least loser was the Muscat Stock Exchange, which fell by 0.5%.
The report stated that "September's performance was within our expectations, with negative performance predominating. Financial performance expectations for the units are no longer driving the markets; rather, it is the repercussions of ongoing instability in our region on global economies. Although predicting October's performance is difficult, we believe it may move in two completely opposite directions. On one hand, October is the month preceding the US midterm elections for the Senate and House of Representatives. This could serve as an incentive to support de-escalation efforts and reach an agreement between the United States and Iran, potentially lowering fuel and food prices in the US and preserving the Republican Party's majority in both chambers. Alternatively, it may be too late, and geopolitical violence could return, not in the form of a full-scale war, but through increased military posturing to save face for the opposing sides. If the first scenario materializes, i.e., an agreement is reached, it could lead to a near-universal rise in all market indices. If the escalation scenario occurs, it would mean a completely opposite performance."
