Officially: Decree-law issued regarding housing finance for eligible housing care recipients
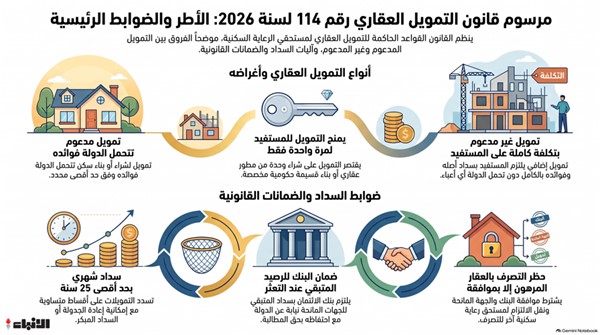
A decree-law regulating subsidized and non-subsidized housing finance for eligible housing care recipients was published under the supervision of the Central Bank of Kuwait.
Translated by Qiyas from الأنباء — Original source
Decree-Law No. 114 of 2026 concerning housing finance for beneficiaries of residential care was issued in the Official Gazette, “Kuwait Today.”
Its provisions are as follows:
Article (1)
In the application of the provisions of this Decree-Law, the following words and phrases shall have the meanings set forth alongside each of them:
- The Competent Minister: The Minister designated by the Council of Ministers.
- The Institution: The Public Authority for Housing Welfare.
- The Bank: Kuwait Finance House.
- The Beneficiary: A person entitled to housing welfare who meets the conditions and controls stipulated by the Bank.
- The Residential Unit: A real estate unit designated for the beneficiary’s residence, with defined boundaries and area, whether independent or part of a larger property, regardless of whether it is already built or planned on a layout.
- Real Estate Financing Entities: Local banks, financing companies, and investment companies subject to the supervision of the Central Bank of Kuwait, whose activities include real estate financing.
- Real Estate Financing: Credit facilities granted by the real estate financing entities to the beneficiary in the form of loans or financing transactions, provided that real estate financing is granted to the beneficiary only once.
- Subsidized Real Estate Financing: Financing provided by the real estate financing entities to the beneficiary to purchase a residential unit from a real estate developer or to construct a government plot allocated by the Institution. The State bears the cost related to the interest or returns accruing thereon. The Executive Regulations of this Decree-Law shall specify the maximum limit for subsidized real estate financing and the associated interest or returns, in accordance with the provisions of Law No. 47 of 1993, referred to above.
- Non-Subsidized Real Estate Financing: Financing provided by the real estate financing entities to the beneficiary to purchase a residential unit from a real estate developer, without the State bearing any cost related to the interest or returns accruing thereon, in accordance with the provisions of this Decree-Law and its Executive Regulations.
- Mortgage: An official mortgage contract that grants the Bank and the real estate financing entities a real right over the property, enabling them to claim their rights from the property ahead of ordinary creditors and subsequent lienholders, in any possession, without prejudice to the provisions of Law No. 47 of 1993, referred to above.
- Real Estate Developer: An entity authorized by the Institution responsible for implementing and developing residential projects to provide housing units that meet the needs of housing welfare beneficiaries.
- Executive Regulations: The Executive Regulations of this Decree-Law.
Article (2)
The provisions of this Decree-Law shall apply to real estate financing provided by the financing entities to the beneficiaries for the following purposes:
- Purchasing a residential unit from a real estate developer.
- Constructing a government plot allocated by the Institution in housing projects, whether already implemented or under implementation, and other plots to be designated by the Council of Ministers.
Article (3)
To be eligible for subsidized real estate financing, the beneficiary must meet the general conditions stipulated in the Mortgage Loans Regulations issued by the Bank for the purpose of purchase or construction.
In all cases, it is a prerequisite that the beneficiary has not previously received housing welfare from the State.
Article (4)
The beneficiary may combine subsidized and non-subsidized real estate financing, observing the controls and procedures established by the Central Bank of Kuwait.
The beneficiary shall be responsible for repaying the principal of both subsidized and non-subsidized real estate financing, in addition to the interest or returns accruing on the non-subsidized financing, in accordance with the terms of the contract concluded with the real estate financing entity and the controls of the Central Bank of Kuwait, while ensuring that the State bears the cost of interest or returns accruing on the subsidized real estate financing in accordance with the provisions of this Decree-Law.
Article (5)
All real estate financings shall be repaid in equal monthly installments, with the term
Repayment shall be made to the grantors of housing finance within 25 years from the date of commencement of disbursement of housing finance with the respective grantor, in accordance with the instructions and controls issued by the Central Bank of Kuwait. The beneficiary may be granted a grace period, as specified in the Executive Regulations, for the repayment of installments, which shall be included within the total repayment period. The beneficiary shall bear the interest or returns accruing on both subsidized and non-subsidized housing finance during the grace period. In cases of early repayment of existing housing finance or a portion thereof, interest or returns shall be waived for the remaining period of the financed housing finance that has been repaid.
Article (6)
The disbursement of housing finance for the purchase of a residential unit from a real estate developer shall be conducted in accordance with the provisions of Law No. (118) of 2023, referenced above. Housing finance for construction on government plots allocated by the institution shall be disbursed in stages of completion, in accordance with the rules established by the Bank.
Article (7)
Grantors of housing finance are obligated to issue a notice to the beneficiary in the event of non-compliance with repayment obligations under the terms of the financing contract. In case of continued non-compliance, they may either restructure the housing finance for a period not exceeding five years, in accordance with the instructions of the Central Bank of Kuwait, with the beneficiary bearing the interest or returns arising from the restructuring of both subsidized and non-subsidized housing finance, or take legal action against the beneficiary.
Article (8)
Grantors of housing finance are obligated to register housing finance cases and submit related documentation to the Bank, including repayment schedules and default cases, in accordance with the instructions and controls issued by the Central Bank of Kuwait for this purpose. The Executive Regulations shall specify the procedures for housing finance, its restructuring, mechanisms for early repayment, the grace period, the definition of default cases and their procedures, and the issuance of notices to beneficiaries.
Article (9)
The Bank, on behalf of the State, shall sign contracts with the necessary grantors of housing finance to implement the provisions of this Decree-Law, in accordance with the provisions and controls stipulated in the Executive Regulations. The Ministry of Finance is obligated to pay the interest or returns due on subsidized housing finance to the Bank from the General Reserve Account. The Bank shall then transfer these amounts to the grantors of housing finance, in accordance with the conditions and procedures specified in the Executive Regulations.
Article (10)
The Bank, on behalf of the State, is obligated to repay the outstanding balance of subsidized housing finance to the grantors in the event that the beneficiary defaults on repayment. In the event that a beneficiary defaults on repayment, the Bank, on behalf of the State, is obligated to pay the accrued interest or returns due on the subsidized housing finance, in addition to repaying the remaining installments of such finance to the grantors, or to pay the remaining installments on their due dates.
If the full balance of the subsidized housing finance is repaid, any remaining future interest or returns are waived from the date of such repayment. The Bank retains the right to claim from the beneficiary all amounts paid toward repaying that housing finance and the associated costs, or a portion thereof.
Article 11
The Bank shall hold the mortgage as consideration for its commitment, on behalf of the State, to the housing finance providers to settle the remaining balance of the subsidized housing finance in the event the beneficiary defaults on repayment. The mortgage on the property shall only be valid if executed through an official mortgage deed, and the property must be specifically and accurately identified in the mortgage deed; otherwise, the mortgage shall be null and void. The registration of the mortgage securing the housing finance shall not be cancelled throughout the duration of the contract, until the full settlement of the debt referred to in the preceding Article.
The Executive Regulation shall specify the model of the housing finance contract, which must include all data and conditions in accordance with the provisions of this Law-Decree and the regulations of the Central Bank of Kuwait pertaining thereto.
The beneficiary shall not dispose of the mortgaged property through sale, gift, or any other form of disposal, nor establish any real right over it, except after obtaining prior approval from the Bank and the housing finance provider. The transferee must be among the eligible recipients of housing care who have not previously obtained housing finance, and must accept to assume the beneficiary’s obligations under the housing finance contract.
The Executive Regulation shall specify the mechanisms and procedures for registering, managing, and disposing of the mortgage.
Article 12
The Bank or any entity designated by the competent Minister may purchase all or part of the housing finance provided to beneficiaries by housing finance providers, based on an agreement with those providers. This finance may be securitized, tokenized, and sold to investors, and may also be repurchased, in accordance with the procedures stipulated in the Executive Regulation and the regulations of the Central Bank of Kuwait and the Capital Markets Authority.
Article 13
The Central Bank of Kuwait shall issue rules and regulations for granting housing finance, including the interest or return rates applicable to non-subsidized finance.
Article 14
The Executive Regulation shall be issued by Decree upon the proposal of the competent Minister within six months from the date of publication of this Law-Decree.
Article 15
The Ministers shall each, within their respective competencies, implement this Law-Decree. It shall be published in the Official Gazette and shall take effect from the date of publication of the Executive Regulation in the Official Gazette.
Subsidized Housing Finance for Plot Construction and Unit Purchase.. Repayment Period Up to 25 Years
Explanatory Memorandum: The State Bears the Interest on “Housing Finance” for Eligible Recipients of Housing Care
The Explanatory Memorandum to Law-Decree No. 114 of 2026 concerning Housing Finance for Eligible Recipients of Housing Care states the following:
The Constitution emphasizes that the family is the foundation of society, based on religion, morality, and patriotism, and entrusts the State with the trust of preserving the family unit, strengthening its bonds, and protecting motherhood and childhood within it. This imposes a full responsibility on the State to address family issues and needs, most notably housing care, and to provide such care in a timely manner by removing the major material obstacles hindering it.
Despite the variety of housing care provided by the State to Kuwaiti citizens, the housing problem continues to worsen due to financial challenges facing the State generally and the Kuwait Credit Bank specifically, resulting from structural imbalances in the economic environment. These challenges have created new risks to the ability to fulfill the commitment to provide decent housing for Kuwaiti citizens in the near future, amid accumulating demand and limited supply.
Law No. 118 of 2023 concerning the establishment of companies for the creation and economic development of cities or residential areas was one of the pillars in addressing the housing problem.
In an effort to enhance the aforementioned law and achieve its objectives, the need arose for a new law to serve as one of the alternatives contributing to solving the housing problem from an economic perspective that ensures the required sustainability.
Given that the Emiri Amiri Order was issued on May 10, 2024, and Article (4) thereof stipulated that laws are to be issued by decree-laws, the present draft Decree-Law was prepared. It comprises 15 articles. Article (1) thereof sets forth definitions that clarify the true meaning of the terms used in its provisions, in order to prevent ambiguity, avert doubts, and close the door to interpretation.
Article (2) specifies the scope of application of the provisions of this draft Decree-Law in an exhaustive manner, and clarifies its applicability for the purpose of purchasing a residential unit from a real estate developer in accordance with the provisions of the aforementioned Law No. 118 of 2023, or for building a government plot allocated by the Public Authority for Housing Welfare in accordance with the conditions and controls it establishes for housing projects, whether those already implemented or currently under implementation, as well as other plots to be determined by the Council of Ministers. The provisions of this Decree-Law do not apply to other purposes, such as expansion, renovation, purchase from non-developers, or construction on private plots not allocated by the Public Authority for Housing Welfare.
Article (3) stipulates the conditions for the beneficiary’s eligibility for subsidized mortgage financing. These conditions include meeting the general requirements set forth in the Mortgage Loans Regulations issued by the Kuwait Credit Bank for the purposes of purchase or construction, and not having previously received housing care from the State, whether in the form of government plots allocated by the Public Authority for Housing Welfare, issuance of a title deed, or receipt of any loans granted by the Kuwait Credit Bank, regardless of their value or purpose.
Article (4) outlines the provisions regarding mortgage financing, whether subsidized or non-subsidized, and the repayment mechanism. It permits combining both types of financing in accordance with the controls and procedures established by the Central Bank of Kuwait. The draft Decree-Law deemed it appropriate not to specify their values, but rather to refer their determination to the Central Bank of Kuwait, for reasons of economic and social security and flexibility in transactions that change as circumstances and the economic environment evolve, thereby avoiding rigid constraints that would be difficult to amend later when necessary.
The same article further clarifies that the beneficiary is responsible for repaying the principal of both subsidized and non-subsidized mortgage financing, in addition to the interest or returns accruing on non-subsidized financing, in accordance with the terms of the financing contract and the Central Bank of Kuwait’s controls. This is subject to the State bearing the cost of interest or returns on subsidized mortgage financing in accordance with the provisions of this Decree-Law.
Article (5) stipulates that all mortgage financings shall be repaid in equal monthly installments, with the repayment period not exceeding 25 years from the date of disbursement of the mortgage financing by the granting institution, in accordance with the instructions and controls established by the Central Bank of Kuwait.
The decree-law authorized granting a grace period for installment payments, as determined by the executive regulations, which is included within the total repayment term of 25 years. During this period, beneficiaries are permitted to request a deferral of the principal repayment for housing finance if they purchase a residential unit from a real estate developer on a planned project or to construct on a government plot allocated by the institution, in order to reduce the financial burden on families, particularly those residing in rented housing. Beneficiaries are required to bear the interest or returns accruing during the grace period. The same article also clarified the case of early repayment by beneficiaries and the consequent waiver of interest or returns for the remaining period of the repaid housing finance.
Article (6) referred the procedures for disbursing housing finance for purchasing a residential unit from a real estate developer to the provisions of Law No. 118 of 2023 concerning the establishment of companies for the creation and economic development of cities or residential areas. The same article specified that housing finance for construction on government plots allocated by the institution shall be disbursed in installments, in accordance with the rules established by the Central Bank of Kuwait.
Article (7) stipulated the obligation of financing entities to notify beneficiaries in the event of their failure to repay the housing finance provided to them, in accordance with the terms of the housing finance contract. In such cases, these entities are authorized either to reschedule the housing finance for a period not exceeding five years, in accordance with instructions from the Central Bank of Kuwait, with the beneficiary bearing the interest or returns resulting from the rescheduling period, whether the finance is subsidized or non-subsidized, or to take legal action against the beneficiary.
Article (8) obligated financing entities to register housing finance cases and submit related documentation to the Central Bank of Kuwait, including repayment schedules and default cases, in accordance with the instructions and controls issued by the Central Bank of Kuwait on this matter. The same article referred to the executive regulations to determine procedures for housing finance and its rescheduling, mechanisms for early repayment, the grace period, default cases and their procedures, and beneficiary notifications.
Article (9) authorized the Kuwait Credit Bank to act as the State’s representative in signing contracts with financing entities, within the limits of the provisions of this decree-law and its executive regulations. It also obligated the Ministry of Finance to pay the interest or returns due on subsidized housing finance to the Kuwait Credit Bank from the General Reserve Account, which then disburses these amounts to the subsidized financing entities, in accordance with the conditions and procedures specified in the executive regulations.
Article (10) determined the Bank’s obligation, on behalf of the State, to financing entities to repay the outstanding balance of subsidized housing finance in the event of a beneficiary’s default.
It was further clarified that in the event of a beneficiary’s default, the Bank, on behalf of the State, is obligated to pay the accrued interest or returns on the subsidized housing finance, in addition to repaying the remaining installments of that finance to the financing entities, or paying the remaining installments on their due dates.
In the event of full repayment of the subsidized housing finance balance, any remaining future interest or returns are waived from the date of such repayment. The same article also stipulated that the bank retains the right to claim from the beneficiary all amounts paid to settle that housing finance and its associated obligations, or any part thereof.
Article (11) clarified that the bank obtains the mortgage in consideration for its commitment, on behalf of the State, to the housing finance providers to repay the remaining balance of the subsidized housing finance in case the beneficiary defaults on repayment. It further specified that the mortgage is only valid if executed through an official mortgage deed. The same article emphasized that the property must be precisely and specifically identified in the mortgage deed; otherwise, the mortgage is void. Additionally, the registration of the mortgage securing the housing finance must not be cancelled throughout the contract period, until the full settlement of the debt referred to in the preceding article.
It was also decided that the beneficiary is prohibited from disposing of the mortgaged property through sale, gift, or other forms of disposal, or from establishing any real right over it, except after obtaining prior approval from the bank and the housing finance provider. The transferee must be among the eligible recipients of housing care who have not previously received housing finance, and the transferee must accept to assume the obligations arising from the housing finance contract in place of the original beneficiary. The same article referred to the executive regulations to determine the mechanisms and procedures for registering, managing, and disposing of the mortgage.
Article (12) granted the Kuwait Credit Bank or any entity designated by the competent Minister the right to purchase all or part of the housing finance provided to beneficiaries by the finance providers, securitize it, tokenize it, sell it to investors, and repurchase it, as one of the investment tools that enhance the economic environment. This is to be carried out in accordance with the procedures stipulated in the executive regulations and the regulations of the Central Bank of Kuwait and the Capital Markets Authority.
Article (13) obligated the Central Bank of Kuwait to issue the rules and regulations governing the granting of housing finance, and to determine the interest rates or returns applicable to non-subsidized finance.
Article (14) emphasized the necessity of issuing the executive regulations for the draft Law-Decree by decree, based on a proposal from the competent Minister, within six months from the date of its publication in the Official Gazette.
Article (15) specified that the provisions of the present draft Law-Decree apply to beneficiaries from the date of publication of the executive regulations in the Official Gazette.
